Payvision and ING have come under scrutiny for their alleged involvement in enabling fraudulent activities conducted by individuals such as Gal Barak (the Wolf of Sofia) and Uwe Lenhoff. This report outlines the key arguments against both Payvision and ING concerning their roles in facilitating these fraudulent schemes.
Payvision’s alleged involvement
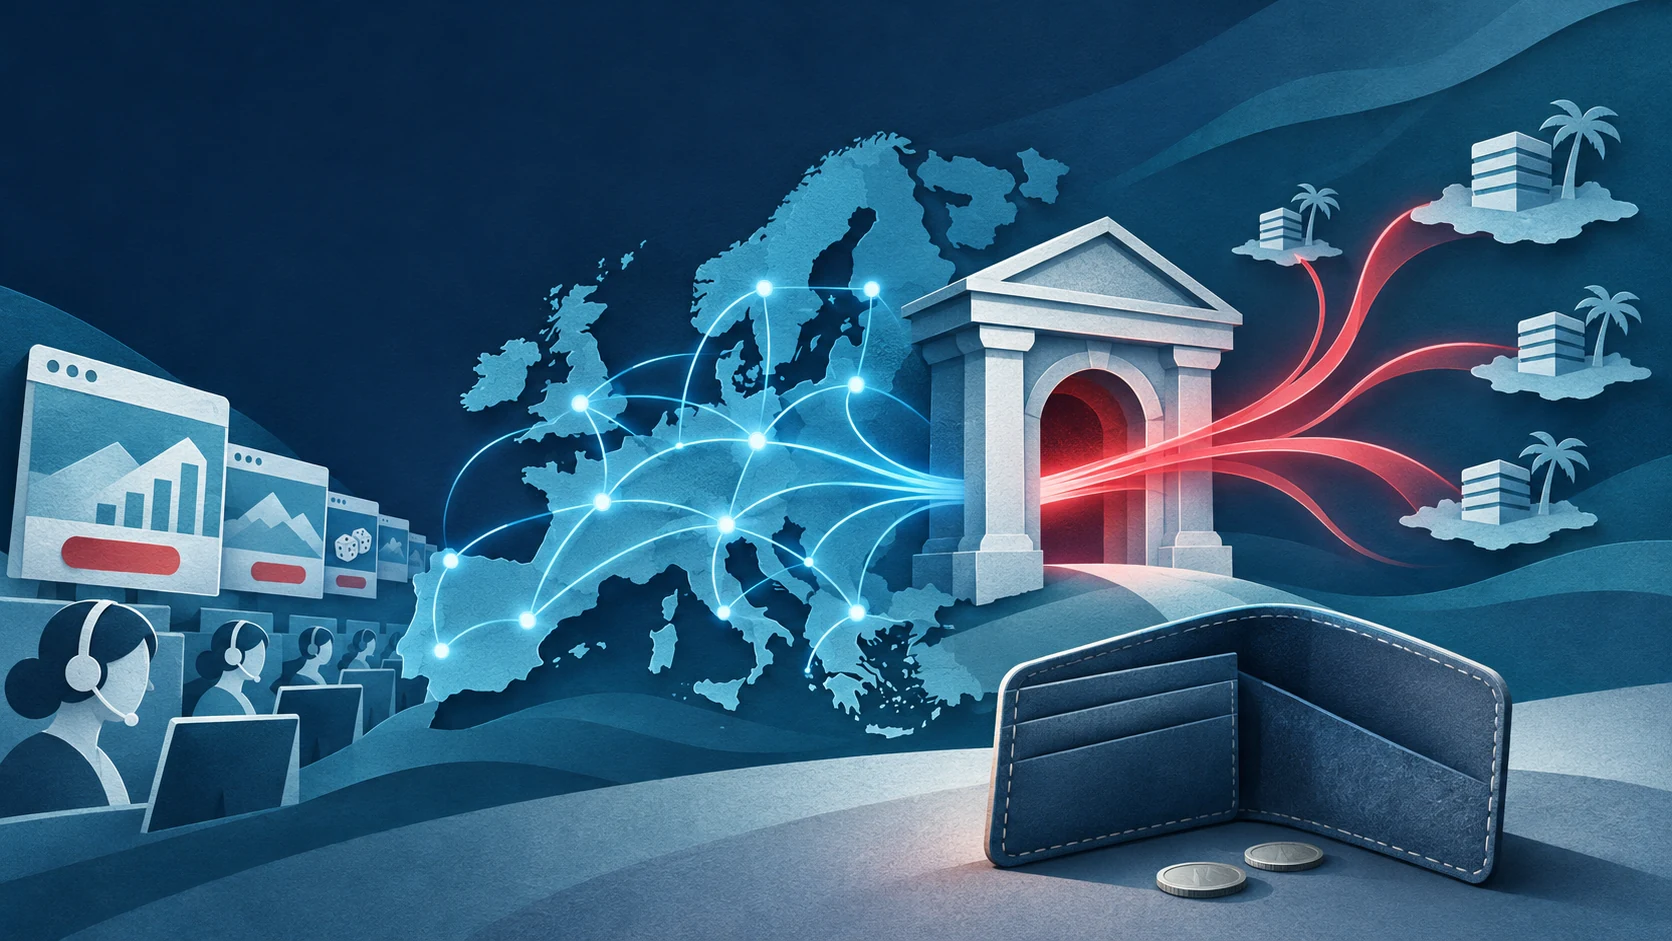
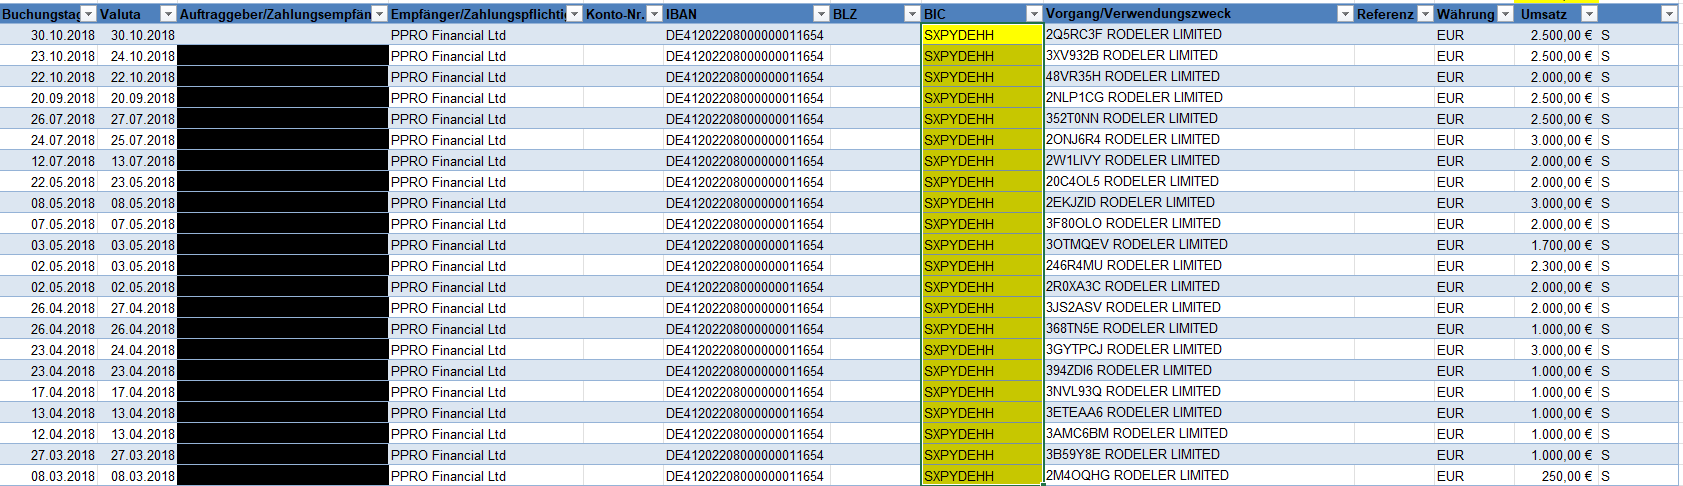
Court files show that Payvision played a pivotal role in enabling Gal Barak and Uwe Lenhoff to accept card payments for their fraudulent websites, which included platforms like xmarkets, option888, Tradovest, Tradeinvest90, xtraderfx, safemarkets, goldenmarkets, and more. Payvision is accused of acting as the main payment processor, processing substantial sums of money on behalf of these fraudulent enterprises.
Violation of Rules and Regulations
It is alleged that Payvision knowingly and deliberately violated Dutch and European authorities’ rules and regulations designed to prevent criminal organisations from exploiting the financial system for fraudulent activities. This breach of compliance forms a central component of the legal claims against the company.
ING’s awareness
ING, a prominent Dutch bank, is accused of being aware of the questionable nature of Payvision’s clientele. Despite this awareness, ING is alleged to have rewarded Payvision with a high valuation in early 2018. Furthermore, it is claimed that ING provided accounts for individuals known as “money mules” who were involved with Gal Barak, Uwe Lenhoff, and other fraudulent schemes.
Breaching the duty of care!
In the Dutch claim brought against Payvision and ING, the victims are seeking compensation for the financial losses they have incurred. They allege that Payvision and ING failed to fulfil their duty of care towards third parties, as mandated by Dutch case law.
The duty of care rule, a fundamental legal concept, requires individuals and entities to exercise reasonable care, skill, and diligence to prevent foreseeable harm to others. It encompasses various aspects of tort, negligence, and contract law. Duty of care has to be applied for relationships between contractors and their customers, and between banks and their clients.
Dutch courts identify a special duty of care rule for banks
Under the Dutch civil legal system, banks are obligated to exercise a duty of care not only towards their direct clients but also towards third parties in specific cases. This duty extends to protecting the interests of these third parties and maintaining the integrity of the financial system. The social function of the bank entails a special duty of care, both in respect of its client and in respect of third parties whose interests should be taken into account by the bank. This special duty of care does not only apply to private clients in the course of the contractual legal relationship, but also to private clients in the pre-contractual stage and in respect of third parties. The scope and implementation of the special duty of care depends on the circumstances of the case. Relevant circumstances are the complexity and risks of the relevant financial product, the knowledge and experience of the client, and the client’s financial position.
Legal Precedents
Relevant legal precedents, such as the “Safe Haven” case (ECLI:NL:HR:2005:AU3713 dated 23 December 2005; defendant Fortis Bank) and a “Ponzi-System” case (ECLI:NL:HR:2015:3399 dated 27 November 2015; defendant ABN AMRO Bank), as well as the Foot Locker/ING Bank case (ECLI:NL:GHAMS:2019:1611), underscore the special duty of care that banks are expected to uphold. These cases emphasise that banks should be vigilant about potential risks and fraudulent activities that could harm third parties.
The Safe Haven case and the Ponzi-System case exhibit several striking parallels to our ongoing legal matter. In both instances, fraudsters utilised bank accounts to collect substantial sums of money from investors for purported portfolio management services despite lacking the requisite authorisation from financial regulators. In both cases, numerous small-scale investors suffered complete financial losses. The Dutch courts determined that the banks had breached their duty of care by failing to conduct timely and thorough investigations after having some hints of irregularities. In both cases, the Dutch Supreme Court found that the banks acted negligently and wrongfully.
None of the money mules using ING bank accounts to collect the victims’ money, and none of Payvision’s onboarded merchants (pure shell companies), had the necessary authorisation from the financial supervisory authorities to sell binary options (qualifying as financial instruments in Europe) to European retail investors.
ING’s arguments presented during its defence in the Foot Locker case were challenged by the court. Despite ING’s reference to factors such as the substantial total volume of payment transactions, the numerous daily FIU reports submitted by ING, and the fact that only a fraction of these reports are ultimately flagged as suspicious by the FIU, the court did not accept these arguments. This was in the context of ING continuing to provide services to an individual who had defrauded Foot Locker of over €1 million, despite having filed a FIU report.
ING also disputed the causal link between the alleged damage and the allegation against ING, arguing that the injury arose due to Foot Locker’s conduct through payment orders validly issued by Foot Locker itself and subsequently executed automatically. Here, the court held that there was a clear unlawfulness and that the damage was foreseeable.
Payvision also filed a lot of FIU reports in connection with Barak’s and Lenhoff’s fraud systems – and continued to service the scammers.
The Supreme Court stresses the social function of a bank and explains that banks – in view of their role in society, their expertise in financial matters and their legal duty to combat financial and economic crime – can be expected to exercise a remarkable degree of care.
Conclusion
In conclusion, our case against ING and Payvision is poised to become an intriguing legal battle. It highlights complex legal and financial issues and underscores the importance of banks’ duty of care towards both their clients and third parties.
However, the assessment always depends on the specific individual case, and with regard to the amount of damages, reference is made here, too, to possible recklessness on the part of the private investor.
Given the extensive volumes of fraudulent transactions processed by Payvision over several years, ING has to fight this case vigorously, as a negative outcome could be devastating.